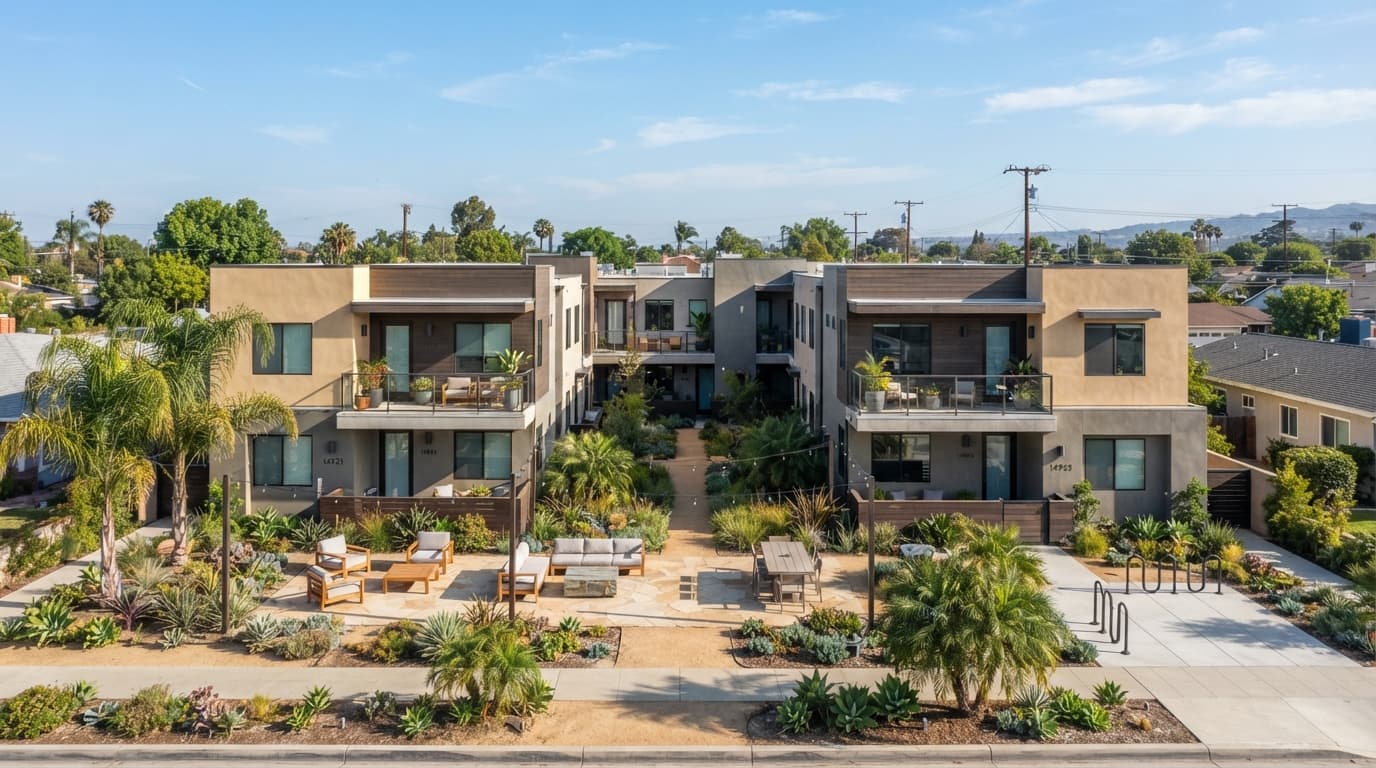
Co-Living Equity Models & Portfolio Expansion: Multi-Unit vs. Infill Co-Investment Strategies
By Global Estate Hub, CA DRE #02039890, Century Financial Group, Corp.
“How co-living, multi-unit and infill co-investment models work, who they suit and what to examine before partnering with others on property.”
Real estate investing has a conventional starting point: buy a rental, collect rent, repeat. As portfolios grow and markets become more expensive, many investors explore other structures: multi-unit buildings, co-living arrangements and co-investment with partners. Each can expand reach and diversify income, but each comes with its own complexity.
This article explains the major models, in plain terms, as a foundation for further research. It is not an offer of securities or investment advice. Any co-investment involving other people's money has legal and regulatory implications, so consult an attorney first.
Model One: Multi-Unit Ownership
Owning a duplex, triplex, fourplex or larger building spreads vacancy risk across several units. If one unit is empty, the others still produce income. Multi-unit properties can also be more efficient per unit to manage and maintain. Financing for small multi-unit buildings, up to four units, often follows residential guidelines, while larger buildings are usually financed commercially and valued by income.
Key points to evaluate include rent rolls, tenant history, building condition, local rent regulations and the cost of deferred maintenance.
Model Two: Co-Living
Co-living means renting individual rooms or private suites within a shared home or building, with shared kitchens and common areas, often on flexible terms. It can generate higher total rent per square foot than renting the whole property to a single household and can meet demand for more affordable housing options.
The trade-offs are real:
- More tenants mean more turnover, management time and potential conflict.
- Zoning, occupancy limits and building code requirements may restrict the number of unrelated occupants.
- Insurance and licensing may differ from traditional rentals.
- Wear and tear on common areas can be higher.
Always confirm that the property and use are legal before buying.
Model Three: Infill Co-Investment
Co-investment means pooling resources with one or more partners to buy, improve or build on property, often in established neighborhoods where land is scarce. Partners may contribute cash, expertise, credit or labor. The structure might be a joint venture, an LLC or a partnership, each with different legal and tax consequences.
The success of a co-investment often depends less on the property and more on the agreement. Define from the outset:
- Each partner's contribution and ownership share.
- Decision-making authority and voting rules.
- How profits, losses and distributions are allocated.
- Responsibilities for management, funding shortfalls and capital calls.
- Exit provisions, buy-sell terms and dispute resolution.
Comparing the Approaches
Multi-unit ownership is more straightforward and suits investors who prefer control. Co-living can raise income but requires operational skill. Co-investment can expand purchasing power but depends on trust and clear legal documents. Many investors progress step by step, starting with a single property, then adding units, then partnering.
Evaluating Any Deal
- Calculate net operating income and cap rate conservatively.
- Stress-test the numbers for vacancy, repairs and rate changes.
- Compare the cost to acquire or build with the property's likely value upon completion.
- Understand your financing and how it affects cash flow.
- Plan your exit: hold, refinance or sell.
Start by Knowing Your Property's Value
Whichever model you consider, the starting point is an accurate understanding of the asset's current value and potential. That grounds every projection that follows.
A Common Question
What is the biggest risk in a co-investment? Unclear expectations. Most partnership problems come from vague agreements about money, control and exit. A well-drafted written agreement reviewed by an attorney is the most important safeguard.
Request an Automated Valuation to establish your baseline and discuss which investment path fits your portfolio.
Disclosure: This article is general information only and is not legal, tax or financial advice. Please consult your CPA, attorney or lender about your situation. Licensed California real estate professional (DRE #02039890) with Century Financial Group, Corp. (DRE #01930905), 8295 Bolsa Avenue, Midway City, CA 92655.
General information only; not legal, tax, or financial advice. Equal Housing Opportunity. Licensing & fair housing disclosures